

Despite favorable indicators both in the United States and elsewhere, Jefferies Equity Research analyst Kai Erman could not put a “Buy” rating on Aristocrat Leisure stock. His hesitancy was expressed in an investor note published on Wednesday.
Erman allowed that Aristocrat was firming up its U.S. market share, showing stateside momentum, and making inroads in i-gaming overall. “[H]owever we see this largely reflected in consensus forecasts and market expectations,” he wrote.
Although the analyst raised his Aristocrat price target to AU$68 a share from AU$63, he maintained a “Hold” rating on the stock.
Citing “strong product momentum,” Erman increased his expectation of Aristocrat unit installations to 4,800, saying the upper end of the 4,000-5,000 range was also likely achievable in 2027. Given the addition of Lightning Link to the i-gaming portfolio, as well as a “clear product pipeline,” Erman felt Aristocrat would achieve online cash flow just shy of 10%.
Although investors, Erman said, expected 5,000-plus product installations, he still felt the company would beat earnings expectations. He pegged likely 2026 earnings per share at AU$2.63 apiece.
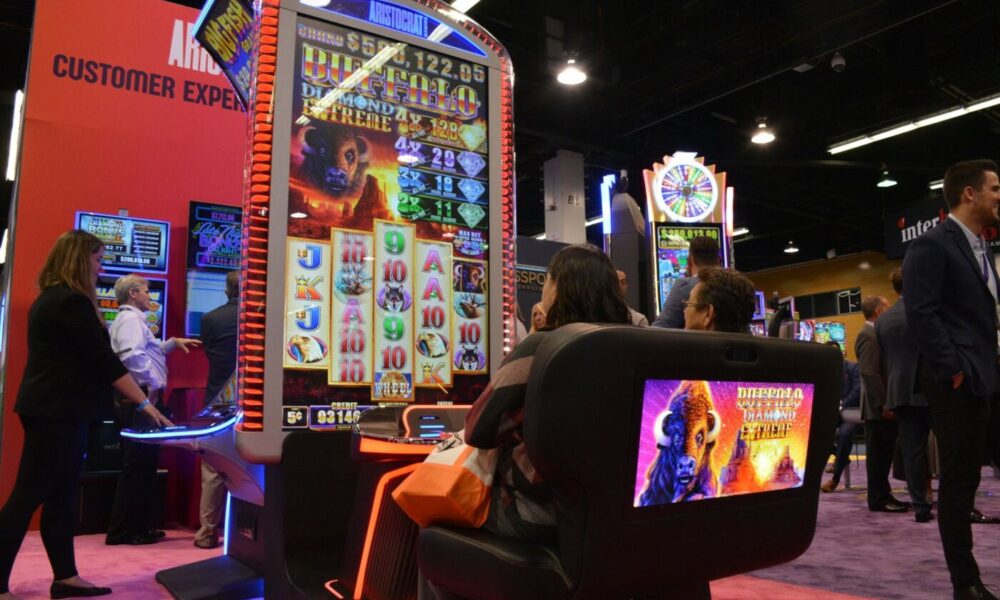
After checking out Aristocrat’s offerings at Global Gaming Expo (G2E) in Las Vegas, Erman said the consensus outlook was that the firm would grow its market share, both within and outside the U.S.
“We agree with this view, although we see limited upside potential to forecasts and expectations for Gaming given high expectations into [2026] result,” he elaborated.
Citing new titles in the Dragon Link, Monopoly and Spooky Link franchises, Erman was of the opinion that Aristocrat’s product lineup “remains robust” and deep, especially when it came to Class II slot games.
Erman felt that rival Light & Wonder could consolidate a second-place position, garnering near-term market share. He saw no other companies making inroads, particularly in leased games, in the next year to two years at least.
Aristocrat, Erman observed, “is seeing strong product momentum in Interactive with successful Lightning Link initial [release].” However, given that such content only represented three percent of the Aristocrat revenue picture, it wouldn’t make much of an impact on the immediate revenue outlook, he wrote.
Still, now that Spooky Link was live online, Erman foresaw 50% revenue growth in 2027, further spurred by the early 2027 release of digital Dragon Link. This would, he said, enlarge the online contribution to 15% of overall revenue by 2031.
Ultimately, Erman’s feelings on Aristocrat were mixed. He felt its “product/content momentum remains strong, but we see this as largely priced in, with limited upside to consensus,” despite having the leading position in the market.
