Subsequent to reviewing new slot product at Global Gaming Expo 2026 in Las Vegas, one analyst had glowing reports on Light & Wonder and Aristocrat Leisure. Jefferies Equity Research analyst Kai Erman published his upbeat views in an October 5 investor note.
Both companies were seen as benefiting from what Erman called a beneficial market structure. He felt Aristocrat was the number-one supplier in the field, growing as well in iGaming and consolidating its top spot in brick-and-mortar gambling.
Of Light & Wonder, Erman said it “has a meaningful opportunity to grow share in key markets which should translate to revenue growth acceleration driven by leased, charitable and international share growth.” Neither game-maker saw any slowdown in revenue, they reported, despite what was thought to be a sluggish August for casinos.
Greater rivalry between casinos on the Las Vegas Strip was described as spurring business for manufacturers, particularly as makers of premium slots. “Higher transport, diesel and labor costs continue to support replacement demand,” Erman added.
The Jefferies analyst met with executives of both companies and found their presentations “compelling.” He was, in particular, impressed with the breadth of the Light & Wonder product stream. Erman cited new Monsters game releases, as well as UFL and Kong revisions.
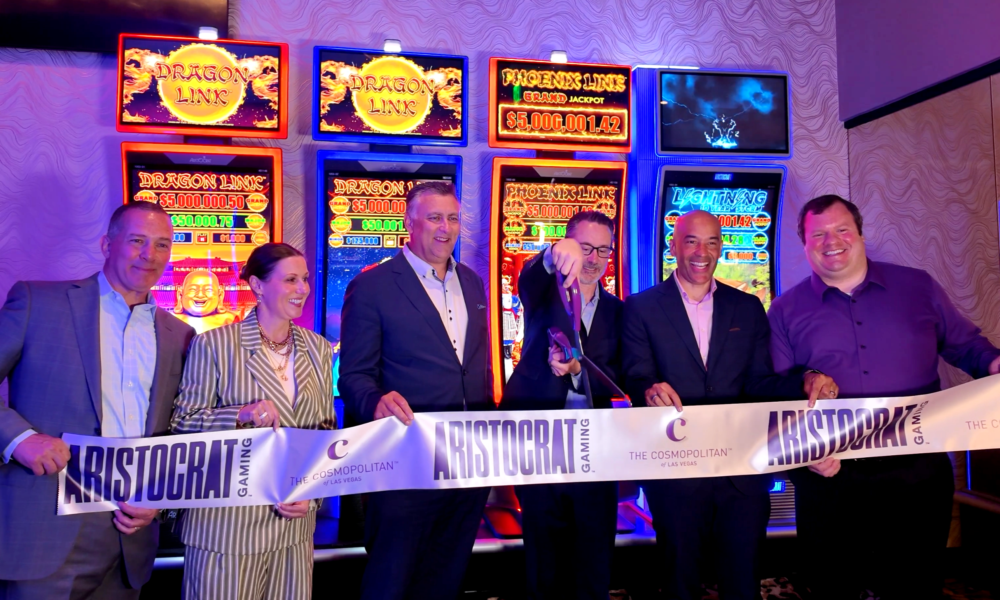
“Reinforcing momentum across both outright sales and participation,” Erman lauded Aristocrat’s unveiling of leased cabinet Reign Double, as well as the sell-through Reign Single. Aristocrat also stated a renewed emphasis on its quartet of Dragon Link games.
Despite predicted, incremental inroads for Light & Wonder, Erman felt that Aristocrat’s top rank was safe. He did, however, note positive customer reaction to Light & Wonder’s Shufflemaster updates and its table-game products.
Aristocrat was seen as, if anything, a victim of its own success. Erman pointed to its 30% floor share and 50% handle share as indications that “incremental floor space is increasingly likely to flow” to rival Light & Wonder. Even so, “we expect Aristocrat to maintain its leadership position across both for-sale and leased gaming.”
As for other suppliers, International Game Technology was in the midst of a high-profile rebranding. Erman found IGT to be pivoting toward the Class II market and to fintech products. IGT management emphasized what it saw as a major opening in Class II, which Erman thought would be complementary to Light & Wonder’s potential share gains in Class III gaming.
Another growth avenue perceived at G2E was charitable gambling. Erman said that Light & Wonder subsidiary Grover Gaming “highlighted a strong product pipeline and faster conversion of traditional casino content into charitable markets.” To that end, Light & Wonder is rolling out a new, charitable-facing game cabinet in 2027.
Light & Wonder also planned a continued, charitable emphasis on its Cascada game, which was live in Kentucky and spreading to Ohio in the fourth quarter. Opined Erman, “the increasing adoption of casino-style mechanics, including progressive jackpots, should support long-term share gains for suppliers with differentiated content.”
Internationally, Light & Wonder also was seen as potent. Losses of market share in Australia and New Zealand were thought by Erman to be reversible on the strength of late-summer releases such as Rolling Drums and Big Steam.
Light & Wonder’s game repertory in the Antipodes was deemed particularly rich, thanks in part to the upcoming, November launches of Frankenstein and Bride of Frankenstein. Both were tailored initially for Australian play, with what Erman described as “unique prize board mechanics.”
iGaming was viewed as an ongoing opportunity for Aristocrat, particularly after the success of its Lightning Link game. The latter “has driven a meaningful improvement in market share rankings since launch, and (Aristocrat) expressed confidence that the franchise can become a durable long-term contributor,” Erman reported.
Light & Wonder, for its part, said Lightning Link had not made a perceptible dent in its own business. The company, Erman opined, “continues to improve its ability to leverage successful land-based content into digital channels.”