

Executives of Gaming & Leisure Properties Inc. were peppered by questions about Bally’s Corp., especially its slowed-down Chicago casino project during their third-quarter earnings call, held Friday. They stood by their development partner.
Calling the City of Chicago’s position on slot routes “unfortunate,” COO Brandon Moore said the suspension of some construction hasn’t changed GLPI’s outlook on the project or its potential performance.
Chief Development Office Steve Ladany added that the incremental Bally’s Chicago amenities were covered in GLPI’s underwriting and that the casino itself was still on schedule. As for the slot routes, CFO Desirée Burke said they were taken into account when GLPI underwrote the project.
“We know that there are close to 1,000 workers and everything’s going at full speed,” Moore said of the $1.7 billion Windy City resort.
“The overall project is roughly two-thirds complete,” noted Ladany, who said the hotel and casino would be weather-tight by December, further accelerating the pace of work.
Regarding the deceleration of the overall project, Moore said it would have virtually no effect on GLPI. “When our dollars are funded, we’re getting paid in real time.” That meant GLPI would be drawing repayment as soon as Bally’s Chicago had cash flow, but that the slowdown might delay Bally’s payday “and impact their financial situation.”
Moore said GLPI wasn’t surprised by Bally’s August going-concern warning, saying that the company has assets it can liquidate to bridge the revenue interim until Bally’s Chicago opens. “I don’t think our overall credit risk has changed. … It’s not something we were excited about.”
Added CEO Peter Carlino, “We have other Bally’s assets in our portfolio and they’re doing fine.”
Moore noted that other parties would be able to step in were Bally’s to falter in Chicago.
Even if Bally’s regional casinos got into trouble, Burke explained that there were certain rent-coverage ratios below which they could not go. Ladany added that GLPI could seize those assets in the event of a default, unlikely though that was.
Senior Vice President of Corporate Strategy Carlo Santarelli answered a question about Bally’s Star Entertainment subsidiary in Australia and its recent AU$260 million fine. “When Bally’s made the investment in Star, it was eyes wide open” and the fine would have no impact on Bally’s proper. He said the issue was isolated to Star, which was turning around financially.
Besides, Santarelli continued, “There is cash there on the balance sheet.” The Australian situation would have no relevance to anything related to GLPI.
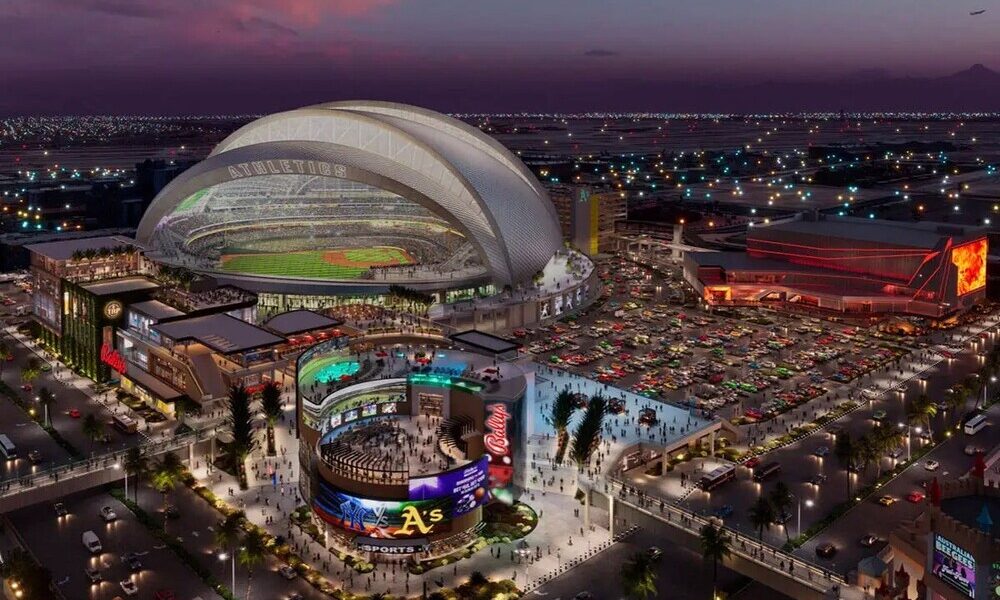
On Bally’s Las Vegas front, Moore said the related Athletics stadium was “progressing nicely.” As for planned Bally’s Las Vegas, GLPI hadn’t been asked for additional financing. “There’s a lot that we need to see before we commit additional capital to it.”
As for other involvement on the Strip itself, Carlino sighed of Las Vegas, “It’s great when it’s great and it’s really crummy when it’s crummy.” Regional casinos, by contrast, “are essentially bulletproof. Time and the decades have proven me right.” He said it was a shame that the outlook on Vegas was negatively coloring people’s view of regional gaming.
Besides Bally’s, the hot topic of conversation was GLPI’s joint venture with Prologis to redevelop the former site of Hollywood Joliet. (See sidebar.) Moore said the deal would generate excess cash beyond what a sale would have done and “perhaps” GLPI would eventually take a larger position in the industrial development. “I won’t say there’s a larger supply of potential sites on our balance sheet,” but GLPI had a few.
“This is a terrific piece of property,” Carlino continued, “and this is going to unfold over a period of years.” He called GLPI “very lucky” to land the transaction, assuring Wall Street analysts that there was “only good news on this one.”
“This was a very unique situation,” noted Ladany, monetizing a real estate asset that wasn’t going to generate a huge return otherwise. But, he said, it was “more of a one-off.”
“I don’t see any downside here at all,” Carlino agreed.
Moore said other joint ventures of a similar nature were possible, but “we haven’t seen anything compelling for our portfolio.” Prologis, he continued, was not a portent of things to come.
Compared to rival Vici Properties, share repurchases were largely off the table for GLPI. “It’s not something that we’re running to do,” said Santarelli, although he remarked that they had been discussed internally.
A buyback, Carlino interjected, was always a last resort, “when you decide to fold your tent. The current [stock] pricing won’t last forever. As long as we can do accretive transactions and put them on the books, we’ll do it.”
Moore lamented that GLPI’s cost of capital had increased at inappropriate levels. The real estate investment trust was, he said, prioritizing the quality of transactions rather than the quantity. Such an example would be “the opportunity to target a category killer” or a property without nearby competition.
Ladany was asked what else might be next for GLPI. He said sale/leaseback transactions were top of mind. “The majority of the [green-field] projects that were floating out there in the universe have been funded.”
